Running a commercial enterprise in Lawrenceville, Snellville, or anywhere across Gwinnett County requires immense dedication, capital, and operational focus.
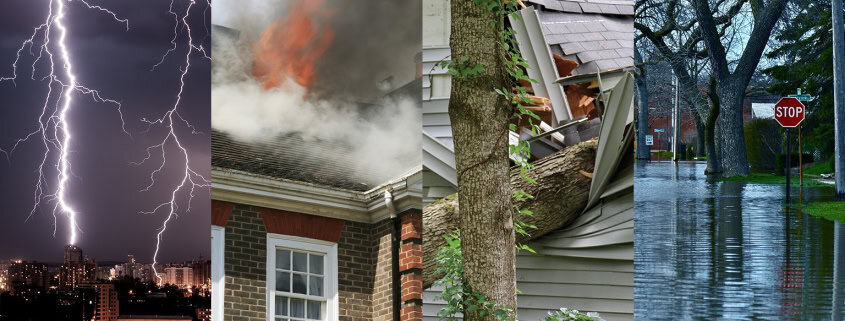
From retail storefronts along Highway 29 and downtown Lawrenceville commercial spaces to sprawling office parks and industrial warehouses, local businesses form the backbone of our regional economy. However, unexpected property disasters such as severe water pipe bursts, roof collapses from torrential storms, sewage backups, or fire and smoke incidents can bring daily operations to a grinding halt in a matter of minutes.
When commercial property damage occurs, many business owners make the mistake of waiting for insurance adjusters or relying on routine janitorial crews to handle cleanup. In the commercial sector, delay is exponentially more costly than in residential properties. Understanding why rapid professional restoration is non-negotiable will help you protect your bottom line, safeguard your physical assets, and resume normal business operations as quickly as possible.
The True Financial Cost of Commercial Business Interruption
Unlike residential water or fire damage where families temporarily relocate, commercial damage threatens the very viability of an enterprise. Every single day or even hour that a business remains closed or restricted creates cascading financial consequences:
- Direct Revenue Loss: If your doors are closed to customers, sales stop immediately. Retail stores, restaurants, medical offices, and service providers cannot generate income while undergoing emergency mitigation unless fast, targeted containment is established.
- Employee Disruption and Payroll Overhead: Salaries and overhead expenses continue to accrue even when operations are paused. Displaced employees face uncertainty, and prolonged shutdowns can lead to valuable staff seeking employment elsewhere.
- Tenant and Customer Attrition: In multi-tenant commercial buildings or retail shopping centers, prolonged property damage frustrates tenants and drives retail foot traffic directly to competing businesses in Gwinnett County.
- Brand Reputation and Client Trust: Service delays, unfulfilled orders, and canceled appointments erode customer trust built over years of dedicated operation. Rapid restoration proves your commitment to reliability and resilience.
How Commercial Damage Escalates Rapidly Over Time
Commercial buildings possess vastly larger square footage, complex multi-story HVAC systems, extensive drywall assemblies, and commercial-grade flooring compared to homes. When water, smoke, or fire breaches a commercial facility, damage escalates at an accelerated rate if professional mitigation is delayed:
- HVAC System Contamination: Smoke soot, chemical vapors, and mold spores are quickly drawn into commercial HVAC return ducts and recirculated throughout the entire building, contaminating unaffected offices and retail zones within hours.
- Extensive Capillary Migration: Water leaking on commercial upper floors quickly saturates drop ceilings, insulation, wiring raceways, and drywall partitions, traveling downward across multiple levels before pooling visibly.
- Aggressive Mold Colonization: In Georgia’s warm, humid climate, moisture trapped inside commercial wall cavities or beneath broadloom carpeting triggers widespread mold germination within 24 to 48 hours, violating health codes and shutting down facilities.
- Corrosion of Electronics and Inventory: Acidic soot from smoke or high humidity from water leaks rapidly corrodes sensitive computer servers, POS systems, electronic equipment, and stored retail inventory if not immediately treated.
Commercial vs. Residential Property Damage: Key Operational Differences
Managing commercial property damage requires specialized commercial-grade equipment, certified project management, and strict regulatory compliance:
| Operational Factor | Residential Property Damage | Commercial Property Damage | Business Impact |
| Scale & Square Footage | Compact footprint (1,500 to 4,000 sq. ft.); single family focus. | Vast square footage (10,000+ sq. ft.); multi-unit or multi-story structures. | Requires industrial-scale extraction fleet and massive dehumidification capacity. |
| Regulatory Compliance | Standard local building codes; private homeowner decisions. | OSHA safety standards, ADA compliance, commercial health & fire codes. | Failure to meet commercial codes results in fines, failed inspections, and liability. |
| Business Continuity | Temporary family relocation; insurance covers additional living expenses. | Revenue loss, payroll continuation, strict customer service deadlines. | Speed is paramount to prevent permanent market share loss and bankruptcy. |
| Coordination & Stakeholders | Homeowner and insurance adjuster. | Business owners, corporate management, commercial landlords, multiple tenants, risk managers. | Requires sophisticated communication and transparent, phased project management. |
Our 4-Phase Commercial Disaster Recovery Process
PuroClean of Snellville & Lawrenceville follows a streamlined, phased approach designed to minimize business interruption and restore commercial properties to pristine operating condition as fast as possible:
- Phase 1: Rapid Emergency Containment and Triage: We deploy an emergency response team 24/7 to secure the building, stop water or smoke intrusion, isolate damaged zones with heavy-duty containment barriers, and protect unaffected business areas so operations can partially continue.
- Phase 2: Industrial Extraction, Air Scrubbing, and Drying: We utilize high-capacity truck-mounted extractors, commercial LGR dehumidifiers, and HEPA air scrubbers equipped with activated carbon filters to purify indoor air and eliminate structural moisture rapidly.
- Phase 3: Content Pack-Out, Cleaning, and Asset Salvage: Sensitive electronics, office furniture, retail merchandise, and vital business records are safely cataloged, cleaned, deodorized, and stored in climate-controlled facilities during structural repairs.
- Phase 4: Complete Reconstruction and Business Handover: Our licensed construction division handles all structural rebuilding including drywall, framing, electrical wiring, flooring, and painting delivering a turnkey commercial property ready for re-opening.
Navigating Complex Commercial Insurance and Business Interruption Claims
Filing a commercial property insurance claim is infinitely more complex than a standard homeowner claim. Commercial policies involve intricate deductibles, coinsurance clauses, pollution exclusions, and business interruption (BI) riders. Proving lost income and operating expenses requires meticulous financial documentation, precise moisture logs, thermal imaging reports, and itemized Xactimate estimates.
PuroClean works hand-in-hand with commercial insurance adjusters, risk managers, and corporate accountants. We provide undeniable photographic evidence, comprehensive scope-of-work documentation, and direct billing support to ensure your claim is processed smoothly and your business interruption coverage is fully leveraged.
Frequently Asked Questions (FAQ) for Commercial Owners
Q: Can my business remain open while commercial restoration is underway?
A: In many cases, yes. By utilizing advanced containment barriers, negative air pressure machines, and scheduling noisy or disruptive restoration work during off-hours, PuroClean can often isolate damaged zones while allowing your primary business operations to continue safely.
Q: What types of commercial properties do you service in Lawrenceville?
A: We service all commercial sectors across Gwinnett County, including retail storefronts, corporate offices, medical clinics, restaurants, warehouses, educational facilities, hospitality complexes, and multi-tenant residential buildings.
Q: How does business interruption insurance work during a property disaster?
A: Business interruption insurance is designed to compensate your company for lost income and ongoing operating expenses (such as rent, utilities, and payroll) during the period of restoration when your facility is unusable. Detailed documentation from a certified restoration contractor is vital to substantiate your claim.
Q: Why should commercial property managers partner with PuroClean in advance?
A: Establishing a Priority Commercial Response Agreement with PuroClean gives your facility pre-loss planning, emergency contact protocols, building mapping, and guaranteed priority dispatch 24/7, drastically reducing downtime when disaster strikes.
Commercial Property Damage in Gwinnett County? Call PuroClean 24/7!
Protect your revenue, employees, and physical assets. Partner with Gwinnett County’s leading commercial disaster recovery experts for rapid, professional mitigation and complete business continuity support.
24/7 Commercial Emergency Hotline: (770) 810-5499
Serving Lawrenceville, Snellville, Grayson, Dacula, Suwanee & All of Gwinnett County
Commercial Water Extraction • Fire & Smoke Mitigation • Mold Remediation • Direct Insurance Billing